


4 minutes ago16 min read


10 minutes ago15 min read


USE THIS SPACE TO PROMOTE YOUR BUSINESS
Financial emergencies and unexpected expenses can arise at any time. Whether you need money for medical treatment, home renovation, wedding expenses, education, travel or debt consolidation, having access to quick financing can make a significant difference. However, arranging funds through traditional borrowing channels can sometimes involve lengthy paperwork, multiple branch visits and complicated approval procedures. This is where digital lending platforms have made borrowing more convenient for Indian consumers. One such lending platform is InCred Finance, which offers unsecured personal loans through a digital application process.
InCred Financial Services Limited provides personal loans to eligible borrowers who need funds for various personal requirements. These loans do not require borrowers to pledge property, gold or other assets as security. According to its official personal loan website, applicants can explore loan amounts ranging from ₹50,000 to ₹15 lakh, depending on their eligibility and credit assessment. The company also highlights digital applications, minimal paperwork and quick disbursement as important features of its lending process.
Before applying, however, understanding the InCred Finance personal loan eligibility criteria and documents required is essential. Your age, monthly income, employment status, credit history and repayment capacity can influence whether your application gets approved. Having the correct documents ready can also help prevent unnecessary delays during verification. In this guide, we explain the eligibility requirements, documentation, charges, application process and practical ways to improve your chances of getting an InCred personal loan in India.
InCred Finance offers unsecured personal loans designed to help individuals manage planned and unexpected financial requirements. Unlike secured loans, these loans generally do not require collateral or a guarantor. This can make them an accessible financing option for eligible salaried professionals and self-employed applicants who have a stable income and can demonstrate their ability to repay the borrowed amount. The digital application journey also allows borrowers to initiate the process without necessarily visiting a physical branch.
One of the main attractions is the loan amount flexibility. The official website currently advertises personal loans from ₹50,000 up to ₹15 lakh, although the final sanctioned amount depends on the applicant's profile and the lender's assessment. Borrowers can also explore repayment tenures of up to 60 months. The application process involves providing personal, employment and financial information, followed by identity and income verification.

Here is a quick overview of the advertised product features:
Feature | InCred Personal Loan |
Loan amount | ₹50,000 to ₹15 lakh |
Loan type | Unsecured personal loan |
Collateral | Not required |
Eligible applicants | Salaried and self-employed |
Minimum monthly income | ₹15,000 net, as advertised |
Age eligibility | 21–60 years on website |
Repayment tenure | 12–60 months |
Application process | Online |
Basic documents | PAN, Aadhaar and last 3 months' bank statements |
Interest rate | Risk-based; check final offer |
These features make InCred worth considering for borrowers looking for digital access to personal credit. However, a quick application does not guarantee approval. Your actual interest rate, processing fee, loan amount and repayment conditions will be communicated based on your individual credit assessment.
Before approving a personal loan, InCred Finance evaluates whether an applicant meets its basic eligibility requirements and has sufficient financial capacity to repay the loan. The lender considers several factors, including age, income, employment profile, credit history and existing financial obligations. Meeting the minimum eligibility conditions is an important first step, but it does not automatically guarantee loan approval. The final decision depends on the lender's internal credit assessment and verification of the information provided in the application.
According to the current official InCred personal loan webpage, the primary eligibility requirements include an age between 21 and 60 years, a minimum net monthly income of ₹15,000 and an employment profile that can be either salaried or self-employed. The lender advertises personal loans up to ₹15 lakh, but the amount offered to an individual depends on their financial circumstances. Applicants should also maintain a satisfactory repayment history and provide accurate personal and financial information during the application process.
Here is a summary of the basic requirements:
Eligibility Parameter | Requirement |
Nationality | Indian applicants |
Minimum age | 21 years |
Maximum age | 60 years on the official website |
Minimum net monthly income | ₹15,000 |
Employment type | Salaried or self-employed |
Credit score | A healthy credit profile is beneficial |
Loan amount | ₹50,000–₹15 lakh |
Loan tenure | 12–60 months |
One important detail deserves attention: InCred's Google Play app listing currently mentions an age range of 21–55 years, whereas its personal loan website mentions 21–60 years. The app listing also mentions ₹15,000 monthly in-hand salary for salaried applicants and ₹25,000 business income for self-employed applicants. Since these published eligibility details are not completely identical, applicants should confirm the applicable criteria through the official application journey before relying on a particular age or income threshold.
Apps on Google Play+1
Age is one of the basic factors considered when applying for an InCred personal loan. The official personal loan webpage specifies that applicants should be between 21 and 60 years old. This means that individuals who have completed 21 years can explore the loan facility, subject to the lender's other eligibility requirements. Applicants approaching the upper age limit should pay particular attention to the applicable repayment conditions and the age requirements shown during the application process.
Nationality and identity verification are equally important. The product is intended for eligible Indian borrowers, and applicants must provide valid KYC information to establish their identity. PAN and Aadhaar are among the key documents mentioned on the official website. These documents help the lender verify the applicant's identity and complete the necessary financial and regulatory checks.
Your monthly income plays a major role in determining your personal loan eligibility. Lenders need to establish that you earn enough to manage your regular household expenses, existing EMIs and the additional repayment obligation created by a new loan. InCred Finance currently advertises a minimum net monthly income requirement of ₹15,000 on its personal loan website. Its app listing provides an additional distinction, mentioning ₹15,000 or more in-hand salary for salaried individuals and ₹25,000 or more in business income for self-employed applicants.
However, earning the minimum qualifying income does not mean that you will automatically receive the maximum advertised loan amount. Suppose two individuals earn ₹40,000 per month. One has existing EMIs of ₹18,000, while the other has no outstanding loan obligations. Although their salaries are identical, their repayment capacities are very different. The lender may therefore offer different loan amounts or interest rates to these applicants.
A useful way to prepare is to calculate your monthly disposable income before applying. Consider your take-home salary, rent, household expenses, credit card payments and existing loan EMIs. A personal loan should fit comfortably into your monthly budget rather than becoming another source of financial pressure.
Salaried professionals looking for additional funds can apply for an InCred personal loan if they satisfy the lender's eligibility conditions. Individuals working in private companies, established organisations or other eligible employment categories may be considered based on their income and overall financial profile. A stable monthly salary gives lenders a clearer picture of repayment capacity because the applicant receives regular income through employment. However, the employer's profile, employment continuity and existing liabilities may also influence the credit assessment.
For salaried applicants, the most important preparation is to maintain consistent salary credits in their bank accounts. Your bank statements should clearly show salary deposits and regular financial transactions. If your salary is credited into one account but you submit statements from another account that does not reflect your income, the lender may request additional clarification. Keeping your PAN, Aadhaar and recent bank statements ready can make the digital application process smoother.
Consider an example of an individual earning ₹60,000 per month. If the applicant has a healthy credit history, manageable existing EMIs and stable employment, their financial profile may be more favourable than that of someone earning the same amount but carrying several overdue payments. This demonstrates why lenders look beyond salary figures when evaluating applications. Applicants should provide correct employment details and avoid exaggerating their monthly income or professional experience.
InCred Finance also allows self-employed individuals to apply for personal loans. This is useful for business owners, consultants, independent professionals and individuals who earn income through their own business activities. Unlike salaried employees, self-employed applicants may not receive a fixed monthly salary. Their earnings can fluctuate depending on business performance, customer payments and seasonal demand. Consequently, documenting income and demonstrating financial stability become especially important during the loan assessment process.
The InCred app listing mentions a business income threshold of ₹25,000 for self-employed applicants, while the official website displays a general minimum net monthly income of ₹15,000. Applicants should confirm which threshold applies to their particular profile and loan product.
Self-employed borrowers should maintain proper financial records and ensure that their bank statements reflect genuine business-related income. Depending on the applicant's circumstances, InCred may request additional income documents to verify the financial information submitted during the application. These could include income tax returns, business income records or other supporting documents, although the exact requirements should be confirmed directly with the lender.
For example, a consultant earning ₹50,000 to ₹70,000 monthly may have a different income pattern from a shop owner earning a similar amount. The lender may examine the regularity of deposits, existing financial commitments and overall repayment capacity before deciding the eligible amount. Providing clear and consistent financial information can help avoid unnecessary verification delays.
Documentation is an important part of the personal loan application process. Even if you meet the basic eligibility requirements, your application may take longer if important documents are missing, unclear or inconsistent. Fortunately, InCred advertises a relatively simple documentation process. Its official personal loan webpage specifically lists three primary documents: PAN Card, Aadhaar Card and the last three months' bank statements.
Here is a practical checklist of documents you should keep ready before starting your application:
Document | Purpose |
PAN Card | Identity and financial verification |
Aadhaar Card | Identity and address verification |
Last 3 months' bank statements | Income and banking assessment |
Salary slips, if requested | Verification of salaried income |
Form 16 or ITR, if requested | Additional income verification |
Business income records, if requested | Verification of self-employed income |
Additional KYC documents, if requested | Supporting identity or address verification |
The first three documents are specifically listed on InCred's official webpage. The remaining items are examples of supporting documents that may be requested depending on the applicant's profile; they should not be treated as mandatory for every applicant.
Identity verification helps the lender establish that the person applying for the loan is genuine and that the information submitted matches the official records. A PAN Card is an important document because it helps establish the applicant's financial identity. Aadhaar is also listed by InCred as a required document for its personal loan application. Applicants should ensure that their personal details, including their name and date of birth, are consistent across the documents they submit.
Before uploading documents, check whether the information is readable and up to date. Blurred photographs, incorrect personal details or mismatched information can create additional verification requirements. If your address has changed, check whether the lender requires any additional supporting address document. Do not assume that an alternative document will automatically be accepted; confirm the acceptable KYC options through the official application process.
You should also protect your personal information while submitting documents. Use InCred's official website or verified mobile application rather than sharing sensitive KYC details through unknown links, unverified agents or social media messages. Never disclose your OTP, banking password or UPI PIN to anyone claiming to help with loan approval.
Bank statements are among the most important documents for evaluating personal loan eligibility. InCred's official website specifically requests the last three months' bank statements. These statements help the lender understand your financial transactions, income deposits, existing loan repayments and general banking behaviour. For salaried individuals, regular salary credits can support income verification, while self-employed individuals may use bank transactions to demonstrate business-related earnings.
If you are a salaried applicant, keep your latest salary slips available in case additional income verification is required. Form 16 may also be useful for supporting your declared employment income and tax information. Self-employed applicants can keep their latest income tax returns, business financial records and other relevant income documents ready if requested by the lender.
One common mistake is submitting incomplete bank statements. For example, uploading only the first page of a statement or providing screenshots that do not show the account holder's name and transaction history may lead to additional document requests. Download complete statements directly from your bank's official website or mobile application whenever possible. Ensure that the selected statement period covers the last three months and that all pages are clearly visible.
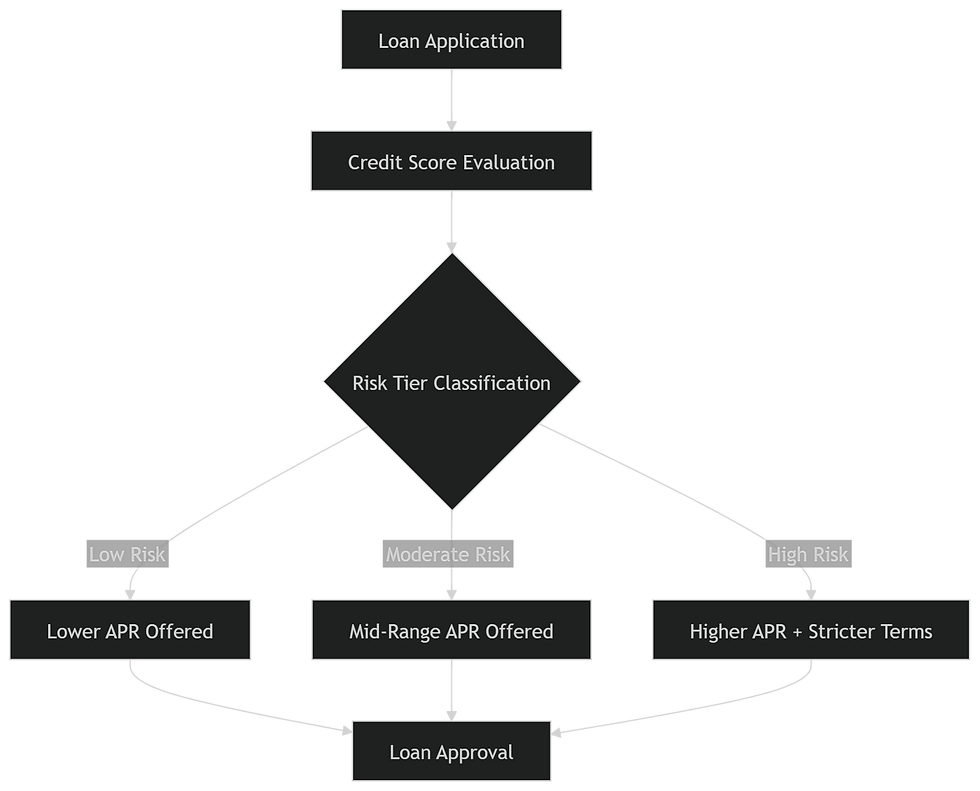
The interest rate is one of the most important factors to evaluate before accepting a personal loan. Since personal loans are generally unsecured, lenders determine pricing based on several factors, including credit history, income stability, existing liabilities and their assessment of the applicant's repayment risk. InCred's official personal loan webpage currently displays an Annual Percentage Rate (APR) range of 14% to 48%. The actual APR offered to an applicant depends on their individual credit assessment.
It is important to understand that the interest rate and APR are not always interchangeable. The interest rate represents the borrowing cost applied to the outstanding principal, while APR reflects the annualised overall borrowing cost, including applicable charges. Therefore, borrowers should compare the complete loan offer rather than selecting a loan based only on an advertised starting interest rate.
The official schedule of charges available on InCred's website lists a processing fee of up to 5% of the loan amount plus applicable taxes. It also lists other possible charges, including late-payment charges, EMI bounce charges and foreclosure or prepayment charges. The applicable charges should be checked against the latest schedule and your individual loan agreement before acceptance.
Charge | Published information |
APR | 14%–48% |
Processing fee | Up to 5% plus applicable taxes |
Loan cancellation | Up to ₹1,000 plus applicable taxes |
EMI/bank account swap | Up to ₹1,000 plus applicable taxes |
Late payment | Up to ₹30 per month per ₹1,000 of overdue principal, on a pro-rata basis |
NACH/PDC bounce | Up to ₹500 per instance |
Part/full prepayment | Up to 5% plus applicable taxes after six months, as per published schedule |
These are published maximum or indicative charges, not necessarily the charges that will apply to every borrower. Always check the sanction letter, Key Facts Statement (KFS) and loan agreement for the actual applicable amounts.
Example of why total borrowing cost matters: Suppose you borrow ₹2 lakh at an illustrative annual interest rate of 18% for 36 months. Your EMI will be approximately ₹7,230. However, if a processing fee and applicable taxes are deducted before disbursement, the amount credited to your bank account will be lower than the sanctioned amount. This is why you should compare the sanctioned loan amount, net disbursal, EMI and total repayment before accepting any offer.
Meeting the minimum eligibility criteria is only one part of getting a personal loan approved. InCred Finance may evaluate several additional financial and personal factors before making its lending decision. Two applicants with similar monthly salaries can receive different loan offers because their credit histories, repayment records and existing financial commitments may not be the same. Understanding these factors can help you prepare a stronger application and avoid common mistakes.
Credit score and repayment history: Your credit score is an important indicator of how you have managed previous borrowing. A strong credit history, timely EMI payments and responsible credit card usage can improve your overall lending profile. InCred's app listing indicates that a credit score of 700 or above is preferable, although this should not be interpreted as a guaranteed approval threshold.
Apps on Google Play
Existing loans and financial obligations: If you already have a home loan, car loan, personal loan or outstanding credit card balance, the lender may consider these obligations while calculating your repayment capacity. Higher existing EMIs reduce the amount of income available for another loan.
Employment and income stability: Regular income provides greater visibility into your ability to repay monthly instalments. Salaried applicants with consistent salary credits and self-employed applicants with documented business income may find it easier to demonstrate repayment capacity.
Accuracy of application details: Incorrect PAN details, mismatched personal information, incomplete bank statements or inaccurate employment information can delay verification or result in rejection.
Ultimately, responsible borrowing and a transparent financial profile are more important than simply applying for the maximum available loan amount.
InCred Finance provides an online application facility through its official website and mobile application. The digital process allows applicants to submit basic personal information and check their eligibility without necessarily visiting a branch. Before applying, keep your PAN, Aadhaar and recent bank statements available so that you can complete the application efficiently.
Follow these steps:
Visit the official website: Open the InCred Personal Loan official webpage and select the option to apply.
Enter your mobile number: Provide your registered mobile number and complete the OTP verification.
Submit personal details: Enter information such as your date of birth, gender, PIN code and PAN.
Provide employment details: Select whether you are salaried or self-employed and enter the requested income and employment information.
Check your eligibility: Submit the application details to view the eligibility assessment.
Complete verification: Upload the required documents and provide any additional information requested by the lender.
Review the loan offer: Check the sanctioned amount, interest rate, APR, processing fee, EMI and repayment tenure.
Accept the agreement: Proceed only after reviewing the applicable loan terms and completing the required digital formalities.
According to InCred's website, eligible applicants may receive an on-screen eligibility result, and a loan executive may contact them within 24 hours. The website also advertises disbursement within 15 minutes of approval. Actual processing and disbursement timelines can vary depending on verification, banking arrangements and other conditions.
After submitting your personal loan application, you may want to know whether it has been approved, is under verification or requires additional documents. Keeping track of your application status can help you respond quickly if the lender requests further information.
Applicants using the InCred mobile application can check available loan updates through the app. You can also refer to communication received through your registered mobile number or email address. If your application remains pending, contact InCred through its official support channels and provide your application reference number.
The official InCred FAQ also provides a WhatsApp customer support option at +91-8655316001. Verify the current support details through the official website before sharing any personal information.
Remember that an application marked as submitted or under review does not mean that the loan has been approved. Final approval depends on successful verification and the lender's credit assessment.
Even applicants with a reasonable salary and stable employment may sometimes face personal loan rejection. This can happen because lenders evaluate the overall financial profile rather than relying on a single eligibility parameter. Understanding the common reasons for rejection can help you correct potential problems before submitting another application.
Some common reasons include:
Low credit score: A poor credit history or repeated repayment defaults may negatively affect your application.
High existing EMI obligations: If a large portion of your monthly income is already committed to loan repayments, your repayment capacity may be insufficient.
Irregular income: Inconsistent salary credits or poorly documented business income may create concerns during verification.
Incomplete documentation: Missing PAN details, Aadhaar information or bank statements can delay or affect processing.
Incorrect application information: Differences between the details entered in the application and supporting documents can trigger verification issues.
Frequent loan applications: Multiple applications within a short period may lead to several hard enquiries on your credit report, potentially affecting your credit profile.
Previous defaults: Unpaid credit card bills, overdue loans or settled accounts may negatively influence lending decisions.
If your application is rejected, avoid immediately applying to several lenders. First, understand the possible reason, review your credit report and correct any inaccurate information. Give yourself time to improve your financial profile before submitting another application.
Improving your personal loan eligibility is not necessarily about earning a higher salary. It is also about demonstrating that you can manage your existing financial commitments and repay additional borrowing responsibly. A few practical financial habits can make your application stronger and help you access more favourable loan terms.
Maintain a healthy credit score: Pay your credit card bills and existing loan EMIs before their due dates. Avoid missed payments because repayment history can influence your credit profile.
Reduce existing debt: If you have multiple outstanding loans, consider reducing your debt burden before applying for another personal loan. Lower monthly EMI commitments can improve your repayment capacity.
Maintain consistent banking transactions: Ensure that your income is regularly reflected in your bank account. Avoid unnecessary irregularities that may make your income difficult to verify.
Provide accurate information: Your PAN, Aadhaar, employment details, income information and bank statements should be consistent. Never provide inflated salary figures or incorrect business income details.
Choose a realistic loan amount: Applying for a loan that matches your actual repayment capacity is generally more sensible than seeking the maximum advertised amount. A smaller loan may result in a more manageable EMI.
Compare the complete loan cost: Before accepting an offer, compare the interest rate, APR, processing fee, net disbursal and foreclosure conditions. A loan with a lower advertised interest rate may not necessarily be the cheapest option after including all charges.
These practices can help you build a healthier credit profile over time. Remember that loan approval is always subject to the lender's policies and individual credit assessment.
InCred Finance offers personal loans to eligible salaried and self-employed individuals looking for funds to manage planned expenses or unexpected financial requirements. With advertised loan amounts ranging from ₹50,000 to ₹15 lakh, an online application process and repayment tenures of up to five years, it provides borrowers with a digital route to personal financing. The official website currently specifies a minimum age of 21 years, a maximum age of 60 years and minimum net monthly income of ₹15,000.
The documents required for an InCred personal loan primarily include your PAN Card, Aadhaar Card and the last three months' bank statements. Depending on your employment profile and verification requirements, additional salary or business income documents may also be requested. Applicants should pay attention to their credit score, existing EMIs and income stability before applying.
Most importantly, do not make your borrowing decision based only on quick approval or advertised loan amounts. Compare the applicable interest rate, APR, processing charges, EMI and total repayment obligation. Read the Key Facts Statement and loan agreement carefully before accepting the offer. Responsible borrowing can help you meet your financial requirements without putting unnecessary pressure on your monthly budget.
According to InCred's official personal loan website, the minimum net monthly income requirement is ₹15,000. However, the mobile application listing separately mentions ₹15,000 in-hand salary for salaried applicants and ₹25,000 business income for self-employed applicants. The applicable requirement should be confirmed during the application process.
The three primary documents listed on InCred's official website are:
PAN Card
Aadhaar Card
Last three months' bank statements
Additional income or KYC documents may be requested depending on your profile.
InCred Finance currently advertises personal loans of up to ₹15 lakh, with loan options starting from ₹50,000. The actual amount sanctioned depends on your income, credit profile and repayment capacity.
Yes. InCred Finance accepts applications from both salaried and self-employed individuals. Self-employed applicants may need to provide additional income documentation to establish their business earnings and repayment capacity.
The official InCred personal loan webpage currently displays an APR range of 14% to 48%. The actual borrowing cost depends on your credit profile and loan assessment. Check the final APR and processing charges in your loan offer before accepting it.
The official personal loan webpage specifies a minimum age of 21 years. It lists the maximum age as 60 years, while the mobile application listing mentions 55 years. Applicants should confirm the applicable age limit through the official application channel.
InCred advertises disbursement within 15 minutes of approval. However, actual disbursement depends on successful document verification, completion of the loan agreement and banking processes.


Comments